Considering a Short Sale? Start Here.
A homeowner's guide to understanding the process, the timeline, the paperwork, the lender review, and what to expect before you make a decision.
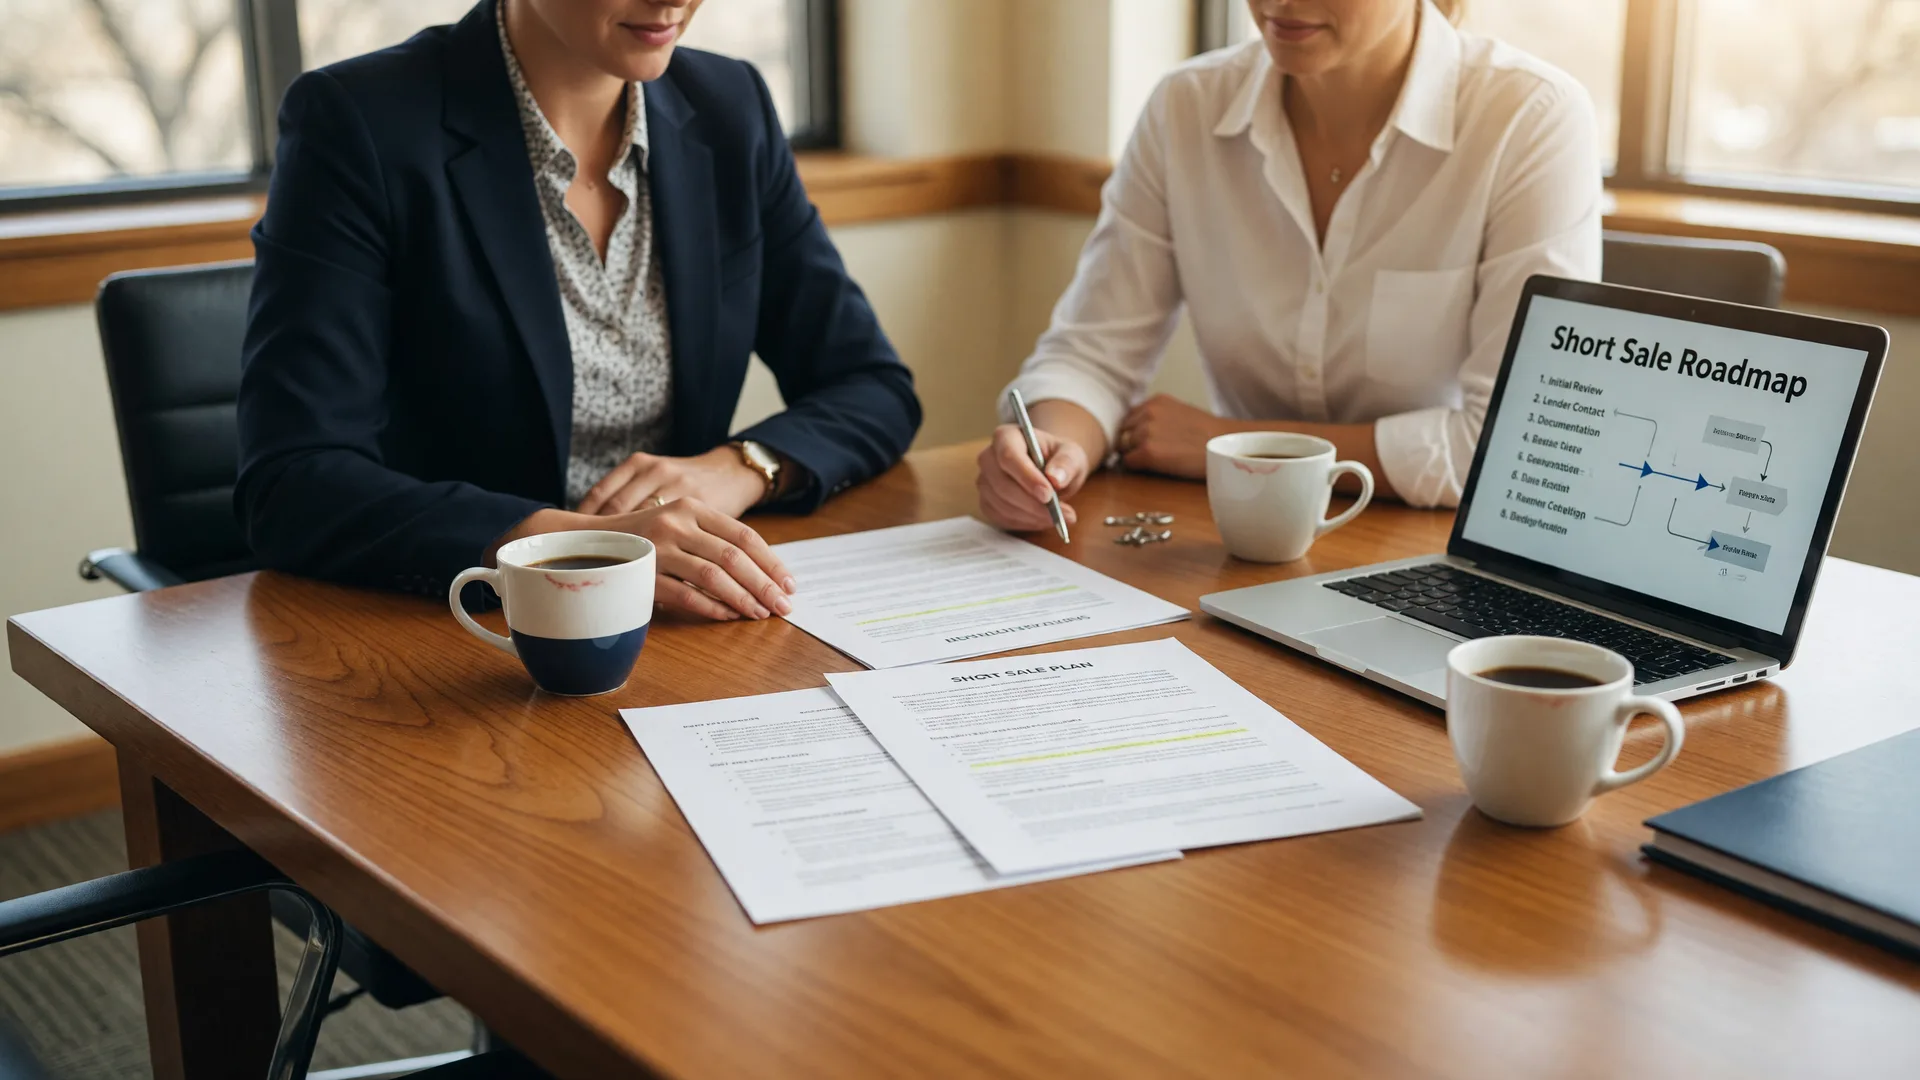
A short sale can help a homeowner sell when available sale proceeds are not enough to satisfy the mortgage debt and other required obligations. But it is not an ordinary sale: it requires the cooperation and approval of the affected lender or lienholder, documentation from the homeowner, a qualified buyer, an appropriately marketed property, and enough time to work through the lender's review process. The earlier you understand the process, the better prepared you can be.
Start here
If You Are Already Behind or Have Received a Foreclosure Notice
Do these three things first:
- 1 Find the latest mortgage and foreclosure documents.
- 2 Determine whether a foreclosure sale has been scheduled.
- 3 Speak with an experienced real estate professional before losing more time.
If you already have a sale date, tell us the exact date when you contact us.
The big picture
A short sale combines a real estate transaction with a separate lender-approval process.
The house still has to be listed, marketed, shown, and sold to a qualified buyer, while the lender or other affected lienholder must separately evaluate and approve the proposed short payoff. That is why short sales require more planning, documentation, communication, and patience than many traditional home sales.
The real estate side
Listing, marketing, showings, an offer, and a qualified buyer moving toward closing.
The approval side
The lender's separate review of the financial situation, the value, and the proposed payoff.
Your situation
Is a Short Sale Right for Your Situation?
Homeowners consider short sales for many reasons. Some of the most common include:
Every lender and investor has its own requirements. A hardship does not guarantee approval, and homeowners do not all have the same short-sale options.
Know your options
Understand Your Options First
Depending on the circumstances, possible alternatives may include:
- Keeping the loan current
- Reinstatement
- Repayment arrangements
- Forbearance
- Loan modification
- Refinance
- A traditional sale
- A short sale
- Deed in lieu of foreclosure
- Other legal or financial options to discuss with the appropriate professional
The purpose of learning about a short sale is not to convince every homeowner to do one. It is to determine whether it makes sense for the individual situation.
The timeline
Be Prepared: A Short Sale Can Take Time
Short sales frequently take longer than traditional sales, because the lender has its own review process in addition to the normal transaction. How long a specific file takes depends on many things, including:
- The lender or servicer
- The investor behind the loan
- Multiple liens
- Whether foreclosure activity has begun
- How quickly documents are provided
- Whether documents must be updated
- Property valuation
- The strength of the purchase offer
- Buyer performance
- Additional lender reviews
- Junior-lien negotiations
- Approval conditions
How the stages usually flow
- 1
Understand the situation
Value, loans, liens, and timing
- 2
List and market
Price the property for the market
- 3
Submit the package
Short-sale file and offer
- 4
Lender review
Valuation, documents, approval
- 5
Approval
Terms reviewed and followed
- 6
Closing
Escrow, title, and recording
These stages often overlap and repeat, especially lender review. A short sale is not a countdown: the timeline depends on the factors listed above.
Be Prepared for Months, Not Just Weeks.
A homeowner should be prepared for a process that may take months rather than weeks.
Longer is not automatically a problem.
Longer does not necessarily mean something is wrong. Short sales often involve periods of lender review followed by requests for additional information or updated documents.
The paperwork
Expect to Provide Financial Documentation
The lender is being asked to accept less than what is owed, so it may require documentation explaining the financial situation and circumstances. Depending on the loan and the lender, requested information may include:
- Financial statements
- Bank statements
- Income information
- Mortgage information
- Hardship documentation
- Authorization forms
- Property information
- Other lender-specific documents
Documentation must be accurate, truthful, complete, and provided promptly. The exact list varies by loan, lender, and situation. See the short-sale documentation guide for the deeper picture.
During a longer short sale some documents may expire or become outdated and need to be provided again. That is normal, not a sign that anything is wrong.
Your part of the process
Your Responsiveness Matters
One of the easiest ways to help a short sale move smoothly is to respond quickly when documentation is requested.
The homeowner is an active participant in the process. When the lender requests updated statements, new signatures, additional information, clarification, or financial documents, delays in your response can delay the lender's review. That is not about anyone doing something wrong: the process moves in steps, and many of those steps wait on documents. Staying responsive keeps the file moving as quickly as the lender's process allows.
If foreclosure is in the picture
Foreclosure Rules Depend on Where the Property Is Located
If foreclosure activity has already begun, timing becomes especially important. There is no single foreclosure timeline that applies nationwide. Foreclosure laws and procedures are determined largely by the state where the property is located, and different states use very different systems, notices, court procedures, deadlines, and sale processes.
Two states, two very different systems
California
Nonjudicial example
- 1 Borrower Contact
- 2 Notice of Default
- 3 Notice of Trustee's Sale
- 4 Trustee Sale
Florida
Judicial example
- 1 Foreclosure Lawsuit
- 2 Court Process
- 3 Foreclosure Judgment
- 4 Judicial Sale
Same problem. Very different state procedures.
Simplified examples for illustration. They are not complete legal timelines, not specific numbers of days, and not a guarantee that either process will follow this exact sequence.
Why this matters
A homeowner pursuing a short sale needs to know what foreclosure process applies in their state, whether foreclosure has already started, what notices or court documents have been received, whether a foreclosure sale has been scheduled, and what important dates are approaching.
The key point
Never assume that starting a short sale automatically stops the foreclosure process.
If foreclosure has already begun, provide all foreclosure notices, court papers, trustee notices, or sale information to the professionals assisting you as soon as possible. See the foreclosure timing guide for the deeper picture.
If Foreclosure Has Already Started
- Save every foreclosure notice or court document.
- Determine whether a sale date has been scheduled.
- Tell the listing agent or short-sale team immediately.
- Provide copies of all notices received.
- Continue opening and reviewing lender and court correspondence.
- Obtain state-specific legal advice when needed.
Disclaimer: Foreclosure laws, procedures, and deadlines vary by state and by individual circumstances. The information on this page is general education and is not legal advice. Homeowners with questions about their legal rights, foreclosure defenses, bankruptcy, or state-specific deadlines should consult a qualified attorney or other appropriate professional in their state.
Pricing
Why the Listing Price Matters
A common question is, "If I owe $600,000, shouldn't we list the house for $600,000?" The lender is primarily interested in market value and expected proceeds, not simply the amount owed.
The property generally needs to be priced based on comparable sales, condition, market activity, competition, location, and buyer demand. The lender may later obtain its own valuation through a BPO, appraisal, automated valuation, or other review, so realistic pricing from the beginning matters.
Read the BPO and valuation guide
The offer
Getting an Offer Is a Major Step, but It Is Not the Finish Line
When a buyer makes an offer:
- 1 The homeowner, through the listing agent, decides whether to accept the purchase offer.
- 2 The short-sale package and proposed transaction are submitted or updated with the lender.
- 3 The lender reviews the offer, expected proceeds, property value, expenses, and other requirements.
- 4 The lender may approve, counter, request changes, request more documentation, or decline the proposed transaction.
Seller acceptance does not equal lender approval.
Both decisions are needed. The homeowner can accept an offer, and the lender can still decline the short payoff. See how short-sale offers work for the full picture.
Valuation
The Lender Will Want to Know What the Property Is Worth
The lender may order a broker price opinion (BPO), an appraisal, or another valuation review. It is determining whether accepting the proposed short-sale offer makes financial sense under its guidelines.
If the lender's value appears unsupported by the market, legitimate market evidence may sometimes be submitted for review. No one controls or manipulates the lender's valuation. The goal is an accurate, well-supported picture of the property's value.
Understand BPOs and valuation reviews
Liens and title
More Than One Loan Can Make the Process More Complicated
A property may have a first mortgage, a second mortgage, a HELOC, an HOA lien, a judgment, a tax lien, or other liens. Some of those parties may also need to approve or release their interest before the property can close, which is why identifying liens early is important.
Approval and closing
What Happens When the Lender Approves the Short Sale?
An approval letter may specify the approved purchase price, minimum lender proceeds, a closing deadline, approved transaction expenses, junior-lien payments, a seller contribution if any, relocation assistance if applicable, and other conditions.
Approval is not simply the word yes. It comes with terms that must be reviewed and followed.
The transaction then moves toward closing under those approved terms. Read the approval letter guide for what each condition can mean.
- Approved purchase price
- Minimum lender proceeds
- Closing deadline
- Approved transaction expenses
- Junior-lien payments
- Seller contribution, if any
- Relocation assistance, if applicable
- Other conditions
Relocation
Could Relocation Assistance Be Available?
Some short-sale programs or lenders may provide relocation assistance to qualifying homeowners. The amount varies significantly and is not guaranteed. Eligibility may depend on the loan type, investor, servicer, occupancy, program requirements, and individual circumstances.
Never assume that relocation assistance is available until it is confirmed in writing as part of the approved transaction.
Short Sale Deal Maker and the listing professional can help identify whether potential relocation assistance should be investigated. No amount is promised here. See the relocation assistance guide for how it works.
See the whole picture
Understand the Financial and Legal Questions
A short sale may affect credit, future mortgage eligibility, remaining debt or deficiency issues, taxes, and other financial obligations. Results vary by state, loan, investor, approval terms, and borrower circumstances.
Short Sale Deal Maker and real estate professionals provide real estate and short-sale process assistance. Homeowners should obtain legal, tax, bankruptcy, or financial advice from the appropriate licensed professional when those issues apply.
What to expect
Common Reasons Short Sales Slow Down
- Missing documents
- Outdated financial documents
- Slow homeowner response
- Lender document requests
- Valuation disputes
- Multiple liens
- Buyer delays
- Buyer financing problems
- Approval expiration
- Foreclosure deadlines
- Changes in the purchase agreement
Good short-sale management cannot eliminate every delay. It can help identify problems earlier and keep preventable problems from becoming bigger ones.
Your checklist
Your Job During the Short Sale
You are not expected to run the file. You are expected to stay involved, stay reachable, and keep the team informed. These ten habits help:
- 1 Stay in contact with the listing agent.
- 2 Respond quickly to document requests.
- 3 Keep financial documents available.
- 4 Forward lender correspondence.
- 5 Immediately report foreclosure notices.
- 6 Keep the property reasonably accessible for showings and valuation appointments.
- 7 Inform the team about significant financial or household changes.
- 8 Do not make side agreements with the buyer.
- 9 Do not assume approval has occurred until it is in writing.
- 10 Ask questions whenever something is unclear.
Choosing help
Why Short-Sale Experience Matters
The traditional sale
A traditional agent primarily manages the sale of the property: pricing, marketing, showings, offers, and the path to closing.
The short sale adds another layer
A short sale also requires understanding lender documentation, servicer requirements, investor guidelines, property valuation, lender review, junior liens, approval conditions, foreclosure timing, and short-sale communication and follow-up. The listing agent does not have to personally do every short-sale task, but the transaction needs a team that understands both the real estate side and the short-sale side.
The listing agent remains your real estate representative. Short Sale Deal Maker helps support the specialized short-sale process.
Nationwide
Homeowners Outside California
Short Sale Deal Maker is a national short-sale education, strategy, and agent-support platform. If the property is outside California, we can help the homeowner understand the general short-sale process and help identify an appropriate local real estate professional where available.
Actual real estate representation is provided by properly licensed professionals according to the laws and brokerage requirements of the state where the property is located.
California homeowners
Is Your Property in California?
If the property is located in California, The Gary Lee Team can provide direct real estate representation. Gary Lee and The Gary Lee Team have extensive experience with distressed-property transactions, short sales, foreclosure situations, and lender negotiations. The team works with homeowners throughout California through eXp Realty of Northern California, Inc.
California homeowners do not simply receive educational guidance. They can talk directly with the team about representation and the specific facts of their property and loan situation.
Gary Lee · CA DRE #01448722 · Rutsell Lee · CA DRE #02067791 · McKayla Lee · CA DRE #02447334 · The Gary Lee Team, eXp Realty of Northern California, Inc.
The Knowledge Center
Want to Go Deeper
This homeowner guide gives the major picture. For detailed explanations, explore:
You Do Not Need to Figure This Out by Yourself.
Every short-sale situation is different. The loan matters. The property value matters. The liens matter. The foreclosure timeline matters. The homeowner's circumstances matter. The earlier those facts are understood, the easier it is to build the right strategy. Tell us what is happening with your property. We will help you understand the next step.
Gary Taylor Lee Jr. · CA DRE #01448722 · McKayla Ann Lee · CA DRE #02447334 · Rutsell Fabillar Lee · CA DRE #02067791 · The Gary Lee Team, eXp Realty of Northern California, Inc.