Skip to content
Short Sale Deal Maker
Home How Short Sale Deal Maker Works Working with listing agents

How Short Sale Deal Maker Works With Listing Agents.

Four disciplines designed to help an agent prepare, position, document, and move a short-sale file through the lender-review process. Short Sale Deal Maker is primarily an agent-support platform: we work alongside the listing agent rather than replacing them.

Last Verified: September 2, 2026 Agent support model Reviewed by The Gary Lee Team before publication

The one-line model

The listing agent handles the real estate transaction. Short Sale Deal Maker helps the listing agent handle the short-sale side of the transaction correctly.

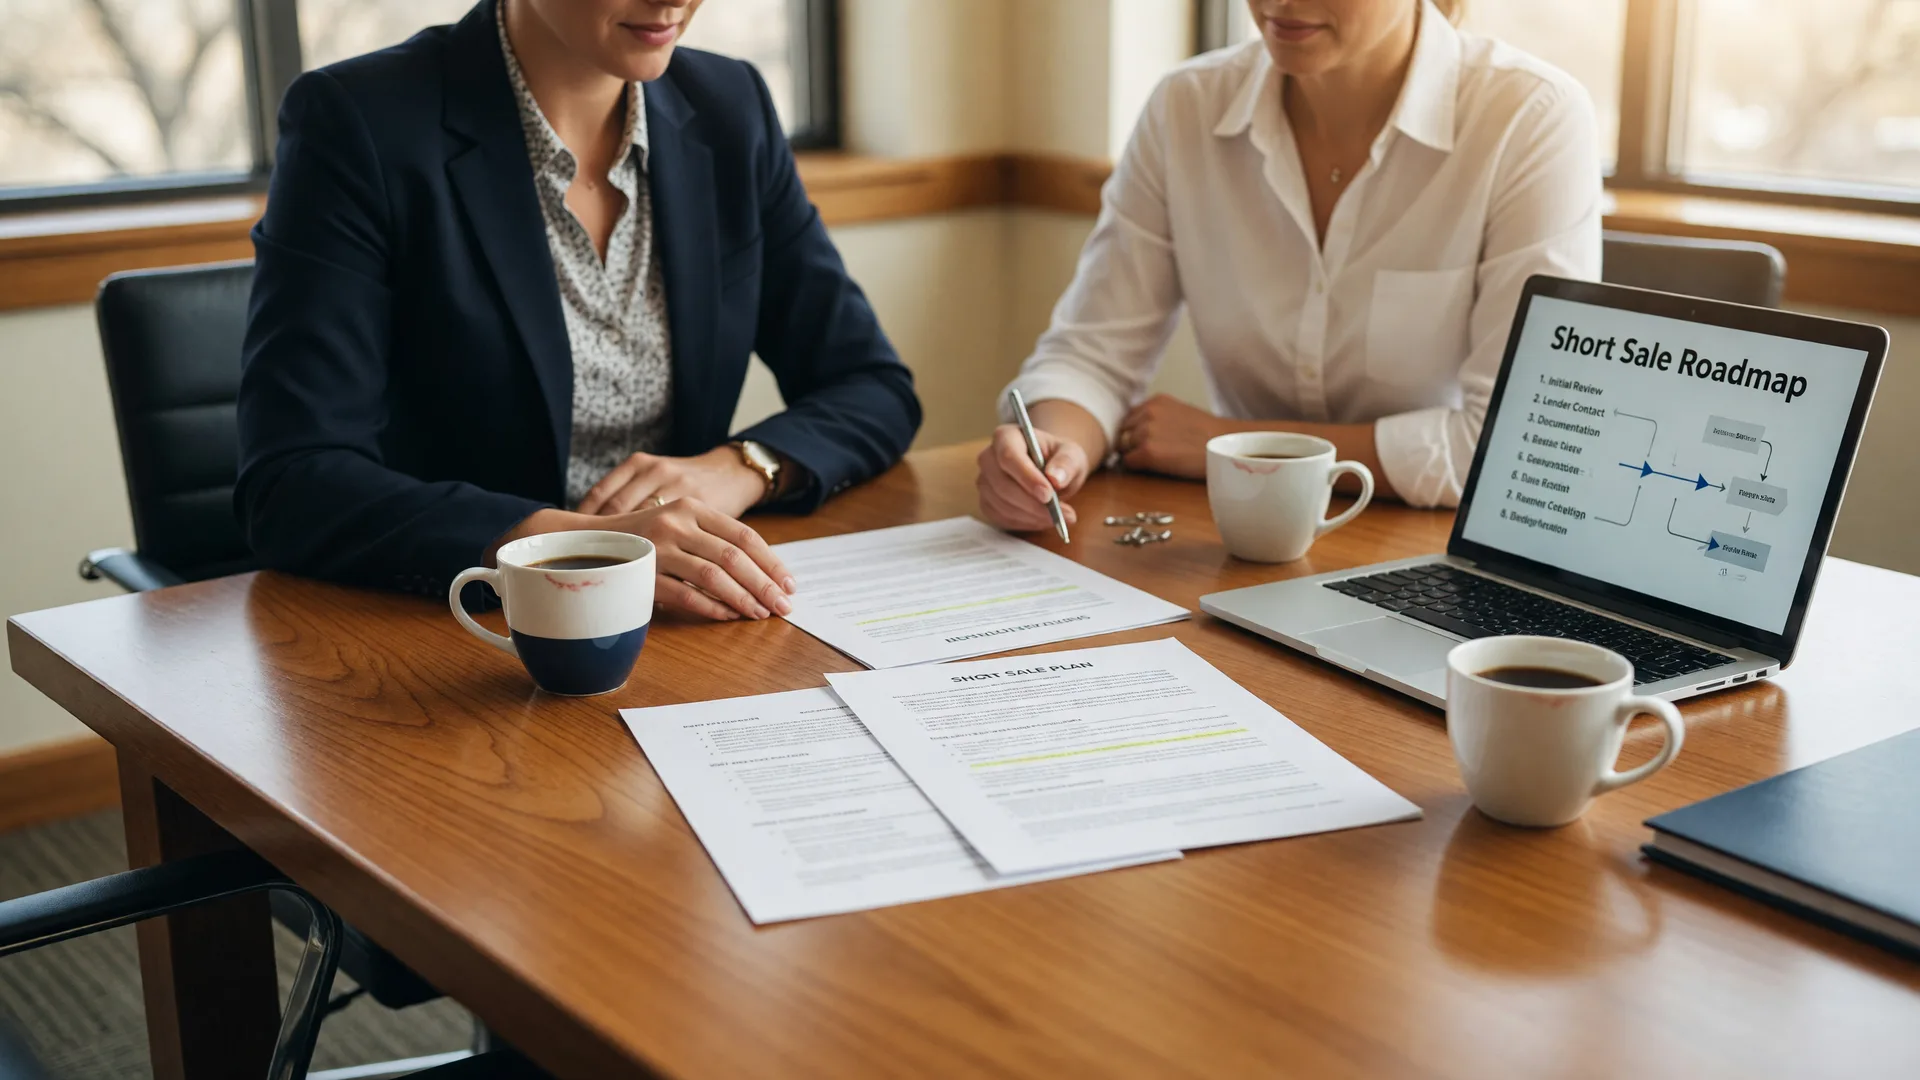
Real estate professional and homeowner reviewing a short-sale plan together at a bright conference table.

An agent-support platform, not a replacement.

Our role is to help the agent understand the short-sale process, prepare the file correctly, collect and organize the required documentation, position the property and the offer with defensible market evidence, and follow the lender or servicer short-sale process from submission through approval.

The agent keeps the real estate side.

The listing agent remains responsible for the listing, the seller relationship, property access, marketing, buyer-side communication, contract duties, and the responsibilities required by the agent's brokerage and applicable law. We support that work from the short-sale side.

Built for real estate professionals

Who does what

The listing agent and Short Sale Deal Maker work as a team.

Two sides, one file. The listing agent handles the real estate transaction. Short Sale Deal Maker handles the specialized short-sale support work. Neither replaces the other.

The boots on the ground

The Listing Agent

Remains responsible for the real estate side, including:

  • Working directly with the homeowner
  • Listing the property
  • Property access
  • Photography and marketing
  • MLS activity and showing coordination
  • Receiving and negotiating purchase offers as the seller's representative
  • Communicating with buyer agents
  • Monitoring the buyer's contractual performance
  • Handling inspections and ordinary transaction issues
  • Helping keep the homeowner informed
  • Obtaining signatures and documents from the homeowner when physical or local assistance is needed
  • Working with escrow, title, the cooperating agent, and other transaction participants
  • Performing duties required by the listing brokerage and applicable law

Short Sale Deal Maker does not take those responsibilities away from the listing agent.

The short-sale support side

Short Sale Deal Maker

Helps with specialized short-sale work, including:

  • Coaching and educating the listing agent
  • Building the short-sale strategy
  • Reviewing loan and lien structure
  • Identifying documentation requirements
  • Helping organize the hardship package
  • Tracking missing or expiring lender documents
  • Helping determine whether the hardship and supporting records are coherent
  • Advising on short-sale timing and listing-price strategy as it relates to lender valuation
  • Helping prepare for BPOs and lender valuations
  • Reviewing offers from a short-sale approval perspective
  • Helping determine whether the offer can be supported by market evidence
  • Helping document property condition and preparing valuation support when appropriate
  • Following the lender or servicer's short-sale review process
  • Responding to lender documentation requests and tracking lender-side milestones
  • Identifying delays and escalation opportunities
  • Helping the listing agent understand what is happening and what needs to happen next

We help manage the short-sale side of the file. The listing agent continues to manage the real-estate side of the transaction.

The work itself

The Four Disciplines of Short Sale Deal Maker.

Everything we do for a listing agent falls into one of four disciplines. Each one supports the agent's own work; none of them replaces it.

01

Educate

We teach the listing agent how to set the short sale up for success.

Goal

Help the listing agent avoid preventable mistakes before those mistakes cost the transaction weeks or months.
Experienced agent coaching another real estate professional through process and market documents.

Education is not simply sending someone to an article. Whenever possible, Short Sale Deal Maker becomes involved before the property is placed on the market. Timing, pricing, presentation, offer structure, hardship-package condition, foreclosure deadlines, and the lender or investor involved can all affect a short sale, and most of those variables are easier to manage early.

We coach the listing agent through:

  • How the process is likely to unfold, step by step (see the short-sale process guide)
  • What to gather before listing
  • Which lender or servicer is involved, and whether junior liens exist
  • Whether foreclosure activity has begun
  • Likely documents, and how quickly they become outdated
  • How hardship must be documented
  • How the property should be priced, and why the lender's valuation matters
  • How a BPO or appraisal can affect approval
  • How offers should be evaluated, and why lender approval differs from seller acceptance
  • Realistic timelines
  • What to communicate to the homeowner
  • What to communicate to prospective buyers and buyer agents
02

Document

A short sale cannot be approved without the documentation necessary to justify it.

Without the required documentation, there may be no complete short-sale file for the lender to evaluate.

What belongs in the package
Two professionals reviewing an organized stack of tabbed short-sale folders together.

Documentation is the foundation of the file. The lender or investor generally needs enough information to evaluate accepting less than the full amount owed. That usually means hardship documentation, financial statements, bank statements, income documentation, tax documents when requested, mortgage statements, junior-lien information, HOA information, property-condition information, listing information, the purchase contract, an estimated settlement statement, authorization forms, and any additional lender-specific documents.

Short Sale Deal Maker identifies what is needed, organizes the file, reviews for missing information, and follows up on incomplete, outdated, illegible, or inconsistent documents.

Where the listing agent is essential:

Some homeowners can scan, upload, sign, and email everything themselves. Others cannot: no scanner, difficulty converting photos into usable documents, trouble uploading, needing help with signatures, locating statements, needing someone local to explain a request, or sending clean, legible copies. That is where the listing agent's boots on the ground are essential, and it is why we build the package around the agent.

The purpose is never to manufacture or embellish a hardship. Documentation must be truthful, complete, consistent, and capable of supporting the homeowner's actual circumstances.

03

Position & Justify

We help position the short sale so the lender can understand why the transaction makes financial sense.

A short-sale offer has to make sense not only to the seller and buyer. It also has to survive lender or investor review.

BPO and valuation guide
Agent building a valuation position with comparable sales, market data and printed reports.

Two things may need justifying. The short sale itself: the file must give the lender or investor enough to evaluate the homeowner's circumstances, which is what the hardship and financial documentation are for. And the offer: the lender is being asked to accept less than owed, so the offer generally cannot be treated like an ordinary purchase offer. The lender or investor evaluates whether the proposed transaction produces an acceptable result based on property value, condition, market activity, comparable sales, expected proceeds, transaction expenses, investor requirements, foreclosure alternatives, and other factors.

Our work can include:

  • Reviewing comparable sales, active and pending competition, property condition, deferred maintenance or material issues, listing history, days on market, and prior price reductions
  • Helping prepare for the lender's BPO or appraisal
  • Reviewing the lender's valuation when available, and helping identify legitimate valuation discrepancies
  • Preparing objective valuation support
  • Reviewing the proposed purchase price and the estimated lender net proceeds
  • Identifying obvious issues that could cause lender pushback, and helping the agent understand whether the offer is defensible

We do not control the lender's BPO, appraisal, valuation model, investor requirement, or approval decision. What we can do is help make sure the lender receives accurate information and that legitimate market evidence is not overlooked. The work is built on objective evidence, actual property condition, legitimate comparable sales, accurate market positioning, and defensible valuation, never on manufacturing a low value.

04

Follow Through

Once the file enters lender review, we stay on the short-sale side of the process.

We stay focused on the short-sale approval process.

Escalation and stalled-file guide
Professional following up on a lender file with a phone, tracking sheet and status board.

A short sale can involve repeated document requests, valuation questions, investor review, title issues, junior-lien questions, approval conditions, expiration dates, and lender follow-up. Our role is to stay on top of that process on the lender side.

  • Confirming receipt of the package
  • Tracking lender and servicer requests
  • Following lender-side milestones and monitoring document expiration dates
  • Identifying missing documents and requesting updates
  • Following up on valuation and investor review
  • Reviewing approval terms and identifying approval deadlines
  • Identifying lender-side problems or delays, and escalating appropriately when escalation is available and justified
  • Communicating important lender developments to the listing agent
  • Helping the agent understand what happens next

In plain English

One model, stated plainly.

We teach the agent. We help build the documentation. We help position and justify the short sale and the offer. We follow the lender-side short-sale process. The listing agent remains the boots on the ground and continues handling the real estate transaction.

That is the Short Sale Deal Maker model.

Honest boundaries

What Short Sale Deal Maker does not control.

Short Sale Deal Maker cannot guarantee short-sale approval, and a successful file depends on many parties doing their jobs. No one can promise their timing or their decision.

  • The seller's lender and mortgage servicer
  • The investor and mortgage insurer requirements
  • Government-program requirements
  • BPO agents and appraisers
  • Foreclosure trustees
  • Junior lienholders, HOA lienholders, judgment creditors, and taxing authorities
  • The buyer, the buyer's lender, the buyer's agent, and the buyer's appraisal
  • Escrow, title, and recording offices
  • Court proceedings and bankruptcy proceedings
  • Government agencies
  • Third-party processing times
  • Approval itself: no one guarantees lender approval

The buyer side stays with the listing agent

Most importantly, Short Sale Deal Maker does not control the buyer side of the transaction. The listing agent must continue communicating with the buyer's agent and monitoring the buyer's performance: financing, inspections, contingencies, appraisal, lender requirements, closing readiness, contract extensions, and the buyer's willingness to continue waiting for approval. Those responsibilities stay with the agent, and nothing on this page should be read as Short Sale Deal Maker taking them over.

The homeowner relationship

The listing agent remains the homeowner's real estate contact.

Short Sale Deal Maker may communicate about documentation and the lender-side short-sale process when appropriately authorized. But the listing agent remains responsible for maintaining the seller relationship within the listing transaction, and continues keeping the homeowner informed about marketing, showings, offers, buyer activity, contract issues, property issues, inspections, buyer performance, escrow developments, and other listing or purchase matters.

We keep the agent informed about important short-sale developments so the agent can communicate with the homeowner.

The engagement path

How a Short Sale Deal Maker file typically works.

Every file is different, but the engagement follows the same six-step shape: prepare, document, position, offer, review, close. It mirrors the short-sale process itself, with the timeline set by the servicer rather than by promises.

  1. 1

    Agent Strategy Call

    Whenever possible, we start before the property is listed. We review loan structure, known liens, the hardship, foreclosure status, property condition, estimated value, timing, documentation, and listing strategy. The objective is to identify problems early and create a roadmap before the transaction gains momentum.

  2. 2

    Build the File

    We determine the likely short-sale documentation and begin organizing the package. The listing agent helps the homeowner gather signatures and documents, especially when hands-on assistance is needed. We review the package for obvious missing, inconsistent, stale, or illegible documentation before and during lender submission.

    Learn what belongs in the package
  3. 3

    Position the Property

    Before and during marketing, we help the agent think through the short-sale implications of pricing, property condition, comparable sales, marketing history, BPO preparation, foreclosure timing, and offer structure. The listing agent remains responsible for the listing and seller representation.

  4. 4

    Review and Support the Offer

    The listing agent represents the seller in handling and negotiating the purchase offer. Short Sale Deal Maker evaluates the proposed transaction from the short-sale approval side: whether the price and the lender net are supported by available market evidence, and which issues are likely to matter during lender review. Seller acceptance does not equal lender approval. The lender or investor makes its own approval determination.

  5. 5

    Follow the Lender Review

    After the package and offer are submitted, we focus on the lender side: requests, documentation updates, valuations, review stages, approval conditions, deadlines, and appropriate escalation opportunities. The listing agent continues managing seller and buyer-side communication.

  6. 6

    Approval and Closing Coordination

    When approval is issued, we review the lender's short-sale approval terms with the appropriate transaction professionals and identify the important conditions: approved sales price, approved lender net, closing deadline, junior-lien allowances, seller contribution requirements if any, relocation provisions if applicable, deficiency language when stated in the approval, and required closing documents. The listing agent, escrow or title company, buyer's agent, buyer's lender, seller, and other participants continue performing their respective closing responsibilities. We do not clear title, confirm all payoffs, close escrow, or record the deed. Those belong to the appropriate transaction professionals.

Timing

Earlier is usually better.

The best time to begin preparing a short sale is often before the property goes on the market. Early preparation gives the agent and the homeowner time to understand the process, identify liens, gather documentation, understand foreclosure deadlines, develop an appropriate listing strategy, prepare property information, set buyer expectations, and address problems before lender review begins.

Starting late does not automatically mean a short sale cannot work. It simply means fewer problems can be solved before deadlines become critical. If you think a short sale may be coming, the earlier conversation costs nothing.

Review the new listing checklist

What early preparation buys you.

Time to understand the process, identify the servicer and investor, map the lien structure, gather and refresh documentation, prepare the property for its BPO, and set buyer and buyer-agent expectations before the first offer arrives. Problems found early are problems that can be solved before the foreclosure timeline makes decisions for you.

Listing strategy

Market evidence, not an artificial number.

Pricing a short sale is not about artificially pricing low to generate an offer, and it is not about simply choosing the amount owed. The listing agent should use legitimate market evidence to establish an appropriate listing strategy.

Short Sale Deal Maker helps the agent understand how listing price, market response, days on market, property condition, comparable sales, and the eventual lender valuation interact, and how each one is likely to read during lender review. See the BPO and valuation guide for the deeper picture.

The goal

A market-supported transaction that can be explained and defended during lender review.

Offer strategy

Seller acceptance and lender approval are different decisions.

The homeowner remains the seller, and the listing agent represents them as the seller's agent. Because the seller is requesting that the lender accept less than owed, the lender or investor must separately decide whether to approve the proposed short payoff. Those are two different decisions made by two different parties.

Short Sale Deal Maker helps the listing agent evaluate whether the offer appears supported by market evidence, whether the proposed lender net is reasonable, whether concessions or credits may create lender issues, whether unusual contract terms may require explanation, whether property condition supports the price, and whether stronger supporting documentation may be needed. We do not accept or reject the buyer's offer on behalf of the seller. That decision belongs to the homeowner and the listing agent.

Why the model works

Why we work through the listing agent.

A short sale combines two different jobs: the real estate transaction and the lender short-sale approval process. Trying to treat them as one creates confusion about who does what, who talks to whom, and who is responsible for what.

The listing agent knows the property, the homeowner, the local market, the buyer activity, the contract, and what is happening on the ground. Short Sale Deal Maker concentrates on short-sale strategy, documentation, valuation support, lender requirements, investor review, lender follow-up, and short-sale approval issues. Together the two sides cover the whole file without stepping on each other.

Listing agent and short-sale specialist working side by side on the same file.

The listing agent does not lose control of the listing. The agent gains a short-sale resource beside them.

Across the country, Short Sale Deal Maker's services are strategy, education, guidance, file review, documentation support, valuation analysis, and coordination. Direct short-sale representation of homeowners is provided by the California-licensed team through eXp Realty of Northern California, Inc. for California files. See the California short-sale representation page for how that works.

Start the conversation

Have a short-sale listing, or think one may be coming?

The best time to talk may be before the property ever hits the market. Bring us the situation. We can help you identify the documentation, timing, valuation, lender, lien, and short-sale issues that should be considered before the file gets underway. You remain the listing agent. We help you build the short-sale strategy behind the transaction.