Junior liens and HELOCs: the deal's quiet veto.
The first mortgage can approve a short sale and the closing can still die, because a junior lienholder said no. This guide explains how second mortgages, HELOCs, and other junior liens affect a short sale, what a short payoff request is, and how a file resolves them. Junior lien and deficiency rights vary by lien type, state, foreclosure method, anti-deficiency law, loan purpose, bankruptcy, and tax status.
Who sits in the junior position
A junior lien is any lien recorded after the first mortgage: a home equity line of credit (HELOC), a second or third mortgage, a judgment, a tax lien, or an HOA assessment. In a short sale the sale proceeds are far too small to pay every lien in full, so each junior lienholder must decide to accept less or stand in the way.
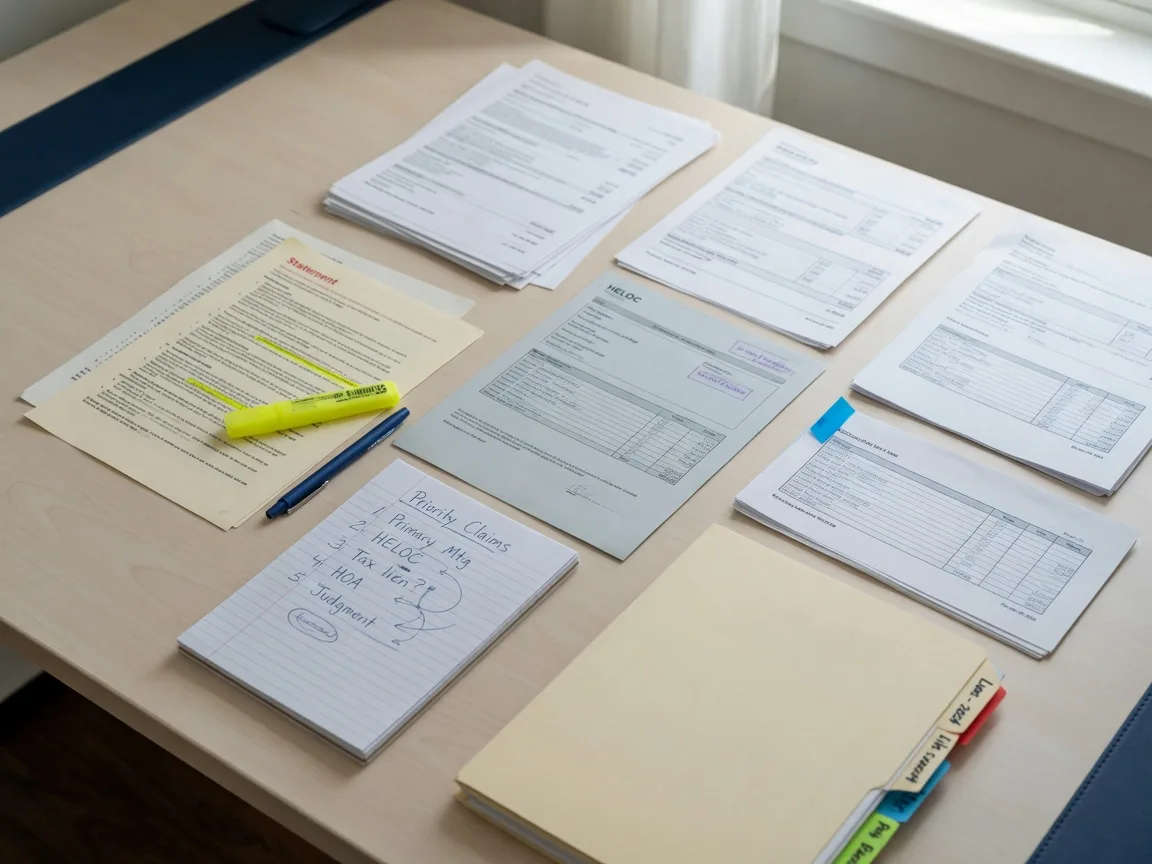
HELOC / second mortgage
Most common junior creditor. Must be paid, released, or negotiated to a short payoff.
Judgment / tax lien
A recorded judgment or tax lien attaches to title and must be resolved before a clean close.
HOA assessments
Unpaid association dues can carry super-priority status and a right to pursue foreclosure.
Why the junior lienholder can say no
In a foreclosure the junior lien is usually wiped out entirely, so a junior creditor may prefer to be patient rather than accept a small cash payment now. Its alternative is to hold its position, let the senior lender foreclose, and receive nothing. That math is why a well-presented short payoff request can work: some value today beats no value after foreclosure.
The senior lender can establish how much it will permit to be paid from the transaction; it cannot necessarily compel the junior creditor to accept a given payoff, and release and payoff agreements vary. Under some approved short-sale structures the senior investor may direct how proceeds are distributed, but the junior creditor's release is governed by its own agreement and applicable law. Where no structure forces the issue, the junior lienholder negotiates freely.
What a short payoff request is
A short payoff request asks the junior lienholder to release its lien for less than the full balance. The file sends a payoff demand letter, the settlement statement, and often a comparison showing the junior creditor where it lands with and without the sale. A few practical realities:
Prepare the case. Show the junior creditor the alternative: a foreclosure extinguishing its lien for nothing.
Expect negotiation. The first number is rarely the last. Escalate to the creditor's portfolio or loss mitigation department, not just collections.
Get it in writing. The negotiated release must be documented and recorded or the lien can follow into the new title.
When a junior lien blocks the deal
If the junior creditor refuses, the senior servicer may still approve the short sale only if the borrower or the deal absorbs the unpaid balance, which often kills the transaction. The professional answers are the ones this site exists to help with: negotiating the short payoff, presenting the foreclosure math, or restructuring the offer so enough net remains to satisfy the junior position. Each deserves experienced eyes.
Start a conversation
A junior lien is holding up a file?
This is one of the trickiest seats at the table, and one the team has worked across many files. Send the payoff picture for a strategy read.