A short-sale house can be a great deal. It can also be a long deal.
Buying a short sale is different from buying a traditional listing. The seller can accept your offer, but the lender still needs to approve the short payoff. That second approval process can take weeks or sometimes months.
If you are considering a short sale, understand the waiting period before you write the offer. This guide explains who approves the transaction, what the lender is reviewing while you wait, how long lender review can take, and how to stay prepared so you can close when approval arrives. It is written for buyers and for the buyer agents who keep them informed.
Set expectations early
Before You Write a Short-Sale Offer, Know These Five Things.
A short-sale purchase is a real purchase, and it is also a lender review you cannot see. These five realities shape everything that follows. The information on this page is educational, not a promise of a specific outcome.
Read the offers guide- 1
The seller can accept your offer before the lender approves the short sale.
Seller acceptance starts the short-sale process. It is not the same as lender approval, which is a separate decision made later.
- 2
Lender review may take weeks or several months.
There is no fixed national timeline. Every short sale is reviewed on its own, and the timing depends on the servicer’s process, applicable investor or program requirements, file completeness, valuation, liens, and other transaction-specific factors.
- 3
The lender may counter the price or terms.
The lender decides what the short payoff must be, and its number can differ from the price the seller accepted.
- 4
You need to keep your financing and purchase plans flexible while you wait.
Preapproval letters expire, rates can move, and lenders ask for updated documents as time passes.
- 5
Once approval arrives, you may need to close much faster than you waited.
Short-sale approvals usually carry a closing deadline, which can be surprisingly tight after a long review.
Who sells, who approves
You Are Buying From the Homeowner. The Lender Has a Separate Decision.
In a short sale, the homeowner is still the seller. The seller, working through the listing agent, decides whether to accept your purchase offer. That is a real and meaningful step: it puts your offer into the short-sale process.
But because the seller is asking the lender to accept less than the full mortgage payoff, the lender or the investor behind the loan must separately approve the proposed short-sale terms before closing. The lender is being asked to take less than it is owed, so it runs its own review of the seller, the property, the value, and the deal.
Seller acceptance gets you into the short-sale process. It does not mean the short sale has been approved.
What the lender is actually reviewing
Why Can't the Lender Just Answer My Offer in Two Days?
Because the lender is not reviewing only the purchase price. In a typical short-sale file, the lender or investor may also be reviewing:
- The homeowner’s short-sale eligibility
- Required financial and hardship documentation
- File completeness
- The property’s market value
- A BPO or appraisal
- Expected lender proceeds
- Sales costs and commission
- Buyer credits or concessions
- Junior liens and other encumbrances
- HOA or title issues
- Investor requirements
- Mortgage insurance requirements, where applicable
- Other short-sale conditions
Your offer may be one piece of a much larger lender review.
Timing, honestly
How Long Does Short-Sale Approval Take?
There is no single answer, and you should treat anyone who promises a precise timeline with caution. Some well-prepared files can receive a lender decision within a few weeks. Other transactions can take several months. A buyer should be emotionally and financially prepared for a broad range.
In real-world short sales, buyers may encounter anything from a few weeks to several months of lender review. In some complicated files, the process can approach six months or longer. The more useful question than "what is the average" is "what is happening in this specific file."
See the common short-sale questionsWhy pace varies
Why Do Some Short Sales Move Faster Than Others?
The same offer can take very different amounts of time depending on the file. Much comes down to how prepared the file is and what the lender operates under. The lender and investor involved set many of the rules.
Two homes listed as short sales can have completely different approval timelines.
- Whether the seller’s documentation was prepared before the offer arrived
- Which lender or servicer is involved
- Which investor owns the loan
- Whether the lender already has a current valuation
- Whether the lender orders a BPO or appraisal
- Whether the value supports the offer
- Whether documents need to be updated
- Whether there is more than one mortgage
- Whether additional liens need to be resolved
- Whether the lender counters or requests changes
- Whether the buyer changes terms along the way
- Whether additional approval levels are required
The purchase sequence
The Short-Sale Purchase, Step by Step.
This is the sequence a short-sale purchase follows. Notice what is not in it: no stage here has a guaranteed duration. The middle of the line is where the waiting happens.
The short-sale purchase in eight moves
Sequence, not timing- 1
Step 1
Offer
- 2
Step 2
Seller Acceptance
- 3
Step 3
Short-Sale Submission
- 4
Step 4
Lender Documentation Review
- 5
Step 5
BPO / Appraisal
- 6
Step 6
Investor / Lender Review
- 7
Step 7
Approval or Counter
- 8
Step 8
Buyer Closing
Steps 4 through 6: this is where much of the waiting happens
Inside the wait
What Is Happening While I Am Waiting?
Once your offer is accepted and submitted, the file follows a general sequence. The exact order and timing vary by lender and file, but this is the shape of it:
- 1
The seller accepts the buyer’s offer.
- 2
The short-sale package and offer go to the lender.
- 3
The lender checks whether the file is complete.
- 4
The lender evaluates the seller’s short-sale request.
- 5
The lender determines or verifies property value.
- 6
The lender reviews the offer and expected proceeds.
- 7
Additional liens or approvals may need to be resolved.
- 8
The lender approves, counters, requests changes, or declines.
- 9
If approved, the transaction moves toward closing.
A quiet period does not necessarily mean nothing is happening. Some portions of lender review happen behind the scenes.
The difference that matters
Waiting Is Normal. Lack of Follow-Up Is Not.
Lender review can take time, and a slow answer is not automatically a problem. But a file should not simply be submitted and forgotten. An organized process should include:
- Confirmation that documents were received
- Follow-up on lender requests
- Monitoring of the valuation process
- Updated documents when necessary
- Tracking of the lender’s review
- Communication of meaningful developments
There may not be new information every day, but someone should be following the short-sale side of the transaction. If your buyer's agent cannot get a status, the listing side is the right point of contact.
The waiting part of the deal
Patience Can Be Part of the Price.
Here is the hard part of buying a short sale: a buyer who walks away after several weeks may lose the opportunity just before the lender reaches a decision. At the same time, a buyer should not remain in a transaction that no longer works. The goal is informed patience, not blind patience.
The buyer and the buyer's agent should periodically evaluate the transaction together:
Review the full process- Is the file progressing?
- Is my financing still viable?
- Does the property still make sense at this price?
- Has my housing situation changed?
- Is there meaningful communication from the listing side?
If the answers still support the purchase, staying committed can be important.
Know your off-ramps
When Should a Buyer Reevaluate the Transaction?
No buyer is locked into a short sale forever. Your purchase contract and its deadlines still apply, and you retain whatever termination rights your contract gives you. You should never stay in a transaction that has stopped working for you. But a long review by itself is not a reason to walk away. Reassess the transaction when:
- You can no longer qualify for the financing.
- Your housing needs materially change.
- The property no longer makes financial sense at the agreed price.
- The transaction has serious unresolved issues, such as title, lien, condition, or valuation problems that cannot be resolved.
- Your contractual rights or deadlines require a decision.
A long review by itself does not necessarily mean the short sale is failing. Talk to your buyer's agent about the specific deadlines and remedies in your contract before you act.
Stay closable
Keep Your Financing Ready.
Approval can arrive after weeks or months of waiting, and it may contain a specific closing deadline. The buyer who is not ready can lose the close even after the lender says yes. While you wait:
- Stay in contact with your buyer’s lender.
- Keep preapproval information current.
- Avoid major new debt when possible.
- Avoid changing jobs without discussing it with your lender.
- Provide updated financial documents when requested.
- Understand that interest rates may change during the waiting period.
- Be prepared to move quickly once approval arrives.
The short-sale lender may take months to approve the transaction and then give the buyer a comparatively short window to close.
The value question
The Seller's Lender Will Form Its Own Opinion of Value.
You may offer $400,000 and the seller may accept $400,000. That does not guarantee the short-sale lender agrees the property is worth $400,000. The lender may obtain a BPO, an appraisal, an automated valuation, or other market information, and it will judge the offer against its own number.
If it determines the property is worth more than the offer, it may counter at a higher price, require a higher lender net, request additional information, or decline the proposed offer. This is one reason short-sale approval is not immediate.
How BPO and valuation work
The counter
What Happens If the Lender Counters?
Example: you offer $425,000 and the seller accepts. After valuation and review, the lender says it needs $440,000. You do not automatically have to accept the lender's number. Depending on the transaction and your contract:
- You may agree to the lender’s terms.
- The parties may respond with additional market evidence.
- The terms may be renegotiated.
- You may decide the transaction no longer works for you.
This is an educational example, not a promise about any specific outcome. Every possible counter depends on the contract, the file, and the parties involved.
Extra approvals
Sometimes More Than One Lender Must Agree.
If the property has a second mortgage, a HELOC, or another lien, that lienholder may also need to approve the short sale or agree to a settlement before closing. Those additional approvals can add real time to the process on top of the primary lender's review. The listing side works through lien resolution as part of the file. For a closer look, see our guide to junior liens and HELOCs.
Condition, realistically
What "As Is" Means in a Short Sale.
Many short-sale sellers have limited ability to pay for repairs, and lender-approved transactions may restrict certain credits or expenses. That can make a short sale feel like an as-is purchase in practice. But it does not mean every short sale is legally required to be sold as-is, that you cannot inspect the property, or that you have no contractual rights.
Buyers should inspect the property carefully, understand the condition, and review their contractual rights before proceeding. Your buyer's agent can help you read the contract and structure repair or credit requests realistically.
-
Many short-sale sellers have limited ability to pay for repairs.
-
Lender-approved transactions may restrict credits or expenses.
-
The property may need maintenance that a motivated seller simply cannot fund.
-
A buyer should inspect carefully and understand repairs realistically.
Inspections and timing
When Should I Inspect the Property?
When and how you inspect depends on your purchase contract, local practice, any negotiated contingencies, and the timing of lender approval. Some buyers build inspections early, before the lender decides, to protect themselves; others structure inspection timing around approval where the contract permits.
There is a real tradeoff: inspecting early costs money on a property the lender could still counter or decline; waiting protects your budget but shortens post-approval time. Discuss the cost and risk with your own agent before you decide.
Do not assume the short-sale lender will pay for repairs discovered during inspections.
Ask your buyer's agent about
- What the purchase contract allows for inspections and deadlines
- What local practice is for distressed sales
- What contingencies you negotiated and when they expire
- Who pays for the inspection if you never close
The pace shifts
Approval Arrived. What Happens Now?
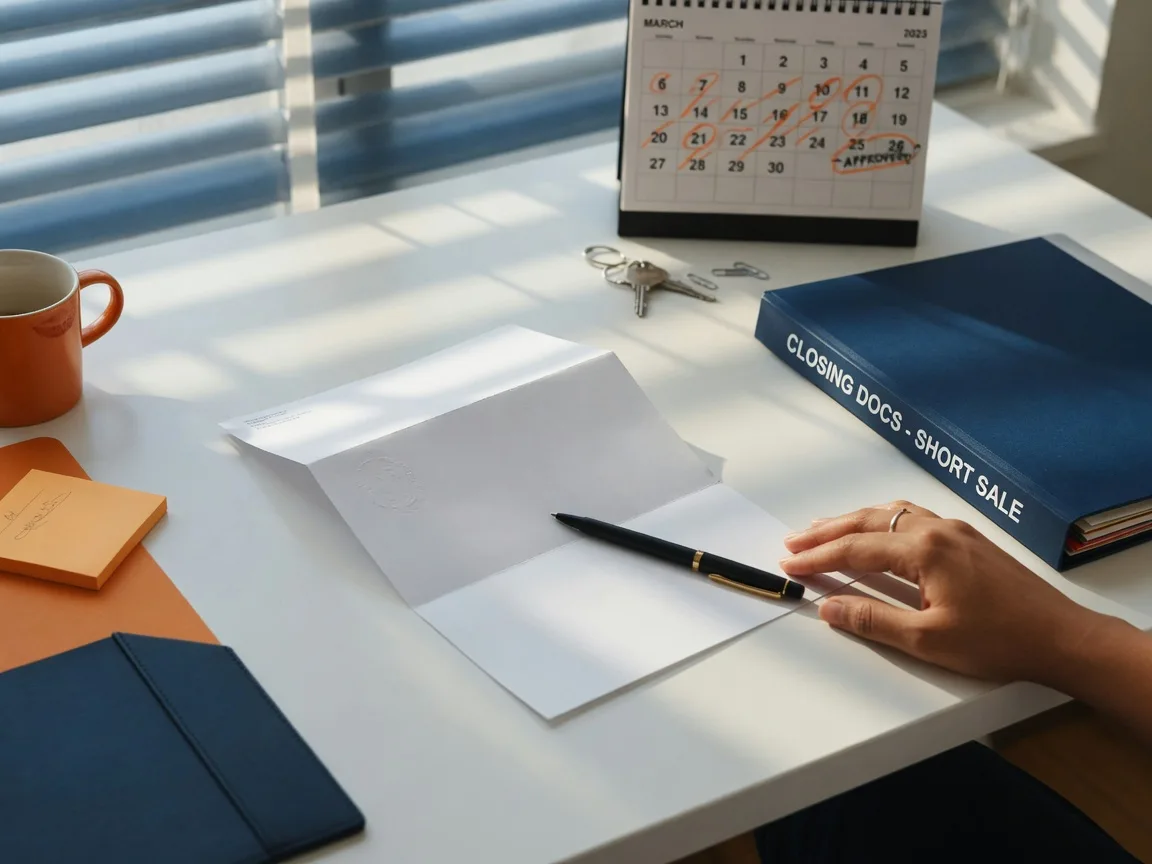
When the lender approves the short sale, the buyer or the listing side typically receives an approval letter that spells out conditions: the approved transaction amount, minimum lender proceeds, a required closing date, approved expenses, and other lender conditions. This is when the transaction can suddenly speed up.
The buyer may need to move quickly on final loan approval, appraisal if not yet done, inspections if still outstanding, insurance, final documentation, closing funds, and escrow requirements. The long waiting period can turn into a comparatively short closing window.
- Final loan approval and updated lender conditions
- Appraisal, if not yet completed
- Inspections, if still outstanding
- Homeowner’s insurance
- Final documentation and signatures
- Closing funds and wiring instructions
- Escrow and title requirements
What strong buyers do
How to Be a Strong Short-Sale Buyer.
-
Enter the process knowing approval may take time.
-
Maintain your financing while you wait.
-
Respond quickly to your lender and your agent.
-
Understand the property’s condition before committing.
-
Stay realistic about repairs and credits.
-
Stay available when approval arrives.
-
Have your buyer’s agent remain in contact with the listing side.
-
Do not assume silence means rejection.
-
Ask for meaningful status updates rather than expecting daily lender decisions.
-
Reevaluate based on facts, not frustration alone.
For buyer agents
For Buyer Agents: Keep Your Buyer Educated and Committed.
The most valuable thing a buyer's agent can do on a short-sale purchase may be managing expectations. Buyers who understand the process before the offer is written are far more likely to stay the course. Before writing the offer and throughout the wait, your job is to:
Talk to the listing side- 1
Explain the approval process before the offer is written.
- 2
Set realistic timing expectations.
- 3
Maintain awareness of the buyer’s financing.
- 4
Explain contractual rights and deadlines.
- 5
Stay in communication with the listing agent.
- 6
Keep the buyer informed through the wait.
- 7
Prepare for possible lender counteroffers.
- 8
Prepare the buyer to move quickly after approval.
- 9
Help the buyer distinguish normal lender delay from a file that has genuinely stopped progressing.
The listing side handles the short-sale lender process. The buyer's agent's job is to keep the buyer prepared, informed, and capable of closing.
Who we are
Where Short Sale Deal Maker Fits.
Short Sale Deal Maker supports the listing side of the short-sale process. Our work concentrates on education, documentation, strategy support, and following the lender process with listing agents, so the file has the best chance of approving cleanly.
We do not represent or control the buyer side simply because a buyer is purchasing one of these properties. The buyer and the buyer's agent remain responsible for the buyer's representation, financing, inspections, contractual decisions, and closing readiness. In California, direct representation is provided by the California-licensed team at eXp Realty of Northern California, Inc.
The Four Disciplines of Short Sale Deal Maker
-
Educate
Understand the process, timing, documentation, pricing, valuation, and lender expectations.
-
Document
Identify, organize, review, and maintain the short-sale documentation.
-
Position & Justify
Support the short-sale request and the offer with legitimate market information.
-
Follow Through
Follow the lender-side process, respond to requests, and keep the listing agent informed.
Plan for the wait
Thinking About Buying a Short Sale?
Understand the waiting period before you write the offer. A short sale can sometimes offer an excellent opportunity, but the buyer needs patience, strong financing, realistic expectations, and an agent who understands how the process differs from a traditional purchase. The seller's lender may take time to make its decision. Your job is to be ready when that decision arrives.
For buyers
Work with your buyer's agent to understand the property, the contract, your financing, and the waiting period.
For buyer agents
Need help understanding what is happening on the short-sale side of one of our files? Contact the listing side for current transaction information.